Overview
In September 2026, global financial markets were shaped by renewed inflationary pressures, higher energy prices, shifting monetary-policy expectations, and heightened geopolitical tensions. The prolonged US–Iran conflict disrupted energy markets, pushing Brent crude above $100 per barrel and raising concerns about a renewed global inflation shock. Rising energy costs and sticky inflation prompted major central banks to adopt a more hawkish stance, contributing to a sharp rise in global bond yields and tighter financial conditions. At the same time, renewed tariff and trade tensions added uncertainty for global supply chains, exports and corporate investment. Equity markets remained mixed and relatively resilient, supported by strong earnings and continued AI investment, although rising yields and stretched technology valuations increased volatility. Overall, September was characterised by a challenging combination of higher energy prices, inflation risks, tighter monetary policy, trade uncertainty and geopolitical tensions, creating a more cautious environment for global investors.
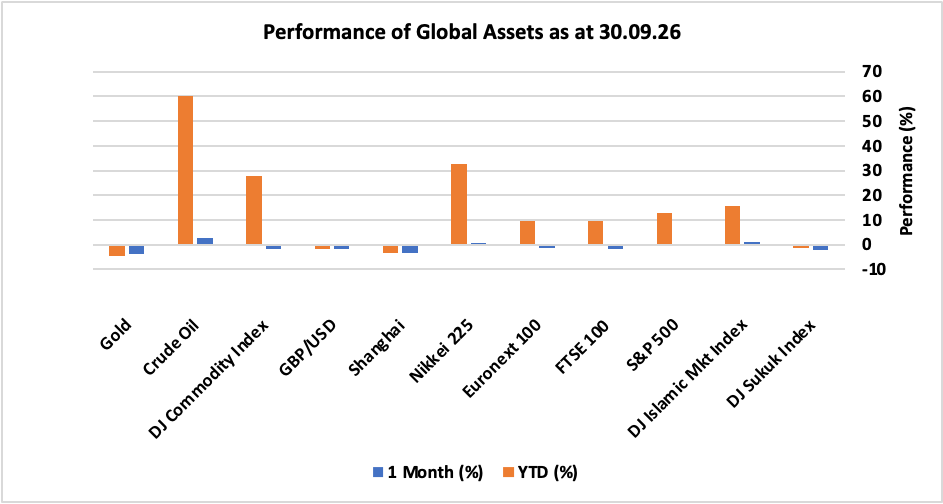
Looking at performance in September, major global financial assets delivered a mixed performance, with U.S. and developed Asian equities gaining while European markets declined amid shifting macroeconomic and geopolitical dynamics and higher oil prices. Commodities fell 1.8%, driven by a 4% decline in gold, despite crude oil rising 2.8%. The S&P 500 rose 0.36%, while the DJ Islamic Markets Index gained nearly 1%, supported by strong earnings from technology and software stocks. Japan’s Nikkei 225 increased by just over 0.8%. Conversely, the UK FTSE 100 fell 1.65%, while Europe’s Euronext 100 declined 1.11%, impacted by rising inflation amid higher oil prices. China’s Shanghai Index plummeted 3.5%. On the fixed-income side, the DJ Sukuk Index fell 2.20% amid rising yields. Finally, the UK pound depreciated 1.84% against the U.S. dollar.
The following snapshot provides a detailed breakdown of the performance of different asset classes in September 2026, as well as their progress year-to-date, offering a comprehensive overview of market dynamics during a period marked by both optimism and lingering uncertainty.
Market Snapshot
News & Key Events in September:
UK
- The UK’s annual inflation rate rose to 3.1% in August 2026, the highest in five months, in line with market expectations and up from 2.9% in July.
- The Bank of England’s Monetary Policy Committee voted 6–3 to keep Bank Rate unchanged at 3.75% at its September 16, 2026 meeting, in line with market expectations. Three members preferred a 25-basis-point increase to 4%, the same as at the July meeting.
- The UK economy expanded by 0.5% quarter-on-quarter in Q2 2026, revised up from 0.4% in the previous estimate, following 0.6% growth in Q1. Services output rose 0.6% (vs 0.7% in Q1), led by professional, scientific and technical activities, which increased 2.3%, and information and communication, which grew 2.5%.
- The UK unemployment rate was unchanged for the fourth consecutive period at 4.9% in the three months to July 2026, defying expectations that it would rise to 5.0%.
US
- The annual inflation rate in the US steadied at 3.4% in August 2026, the same as in July and in line with forecasts.
- The Fed unanimously raised the target range for the federal funds rate by 25bps to 3.75%-4.00% in September 2026 as expected, marking the first rate hike since 2023. Policymakers noted that inflation remains elevated, and the move aims to support a more timely return to the 2% target.
- The US economy expanded at an annualized rate of 2.2% in Q2 2026, revised up by 0.7 percentage point from the 2nd estimate, following an upwardly revised 2.5% growth in Q1. The stronger estimate reflected upward revisions to investment, consumer spending, and government spending.
- The US unemployment rate rose to 4.2% in September 2026, up from 4.1% in August and slightly above market expectations of 4.1%.
Europe
- Eurozone annual inflation accelerated to 3.8% in September 2026, up from 3.2% in August and above market expectations of 3.6%, according to preliminary estimates. The rate reached its highest level since September 2023 and remained well above the ECB’s 2% target, driven largely by a surge in energy prices amid continued fighting in the Middle East.
- The European Central Bank raised its key interest rates by 25 bps at its September meeting, marking its second hike since the US-Iran war began. The ECB said the conflict in the Middle East continues to fuel inflationary pressures, with inflation expected to remain well above its 2% target for an extended period.
- The Eurozone economy expanded 0.6% in Q2 2026, revised up from initial estimates of 0.4%, according to final Eurostat data. It marked the strongest quarterly growth since Q2 2022, driven largely by a sharp upward revision to Ireland’s GDP, which surged 10.2% after plunging 7.8% in Q1.
- The Eurozone’s seasonally adjusted unemployment rate stood at 6.4% in August 2026, holding at the same level since February and matching analysts’ forecasts.
China
- China’s annual inflation climbed to 0.8% in August 2026 from July’s six-month low of 0.5%, in line with market estimates.
- The People’s Bank of China left its key lending rates at record lows for a 16th straight month in September 2026, even as the yuan continued to strengthen and some central banks raised interest rates, in line with expectations.
- China’s economy grew 0.9% qoq in Q2 2026, matching market expectations but easing from a 1.3% gain in Q1. It was the weakest quarterly growth since Q2 2024, as soft domestic demand and the oil shock linked to the Iran war offset resilient exports.
- China’s surveyed urban unemployment rate rose to 5.3% in August 2026 from 5.2% in the previous month, surpassing market expectations of 5.2% and marking the highest reading since March.
Others
- Japan’s annual inflation rate held at 1.9% in August 2026, unchanged from the previous month and remaining at its highest level since December 2025.
- The Bank of Japan raised its key short-term rate by 25bps to 1.25% in a 7-2 vote at its September meeting, taking borrowing costs to their highest level since April 1995. The split decision highlighted growing divisions over the pace of policy normalization as the BOJ responds to persistent inflation, including higher oil prices.
- The headline inflation rate in Canada was unchanged from the previous month at 3.0% in August of 2026, aligned with market expectations and remaining below the post-Iran-war peak of 3.2%.
- The Bank of Canada maintained the target for its overnight rate unchanged at 2.25% in its September 2026 decision, as expected by markets, but flagged stronger upside risks to inflation.
- Russia’s annual inflation rate rose to 6.3% in August 2026, its highest level since November of 2025, up from 6% in the previous month and matching markets expectations.
The Bank of Russia maintained its policy rate unchanged at 14% at its September 2026 decision, aligned with market expectations, after ten consecutive interest rate cuts since departing from the record-high rate of 21% in May of last year. r.
Disclaimer
This article is for information only. Please do not act based on anything you might read in this article. Past performance is not a reliable indicator of current or future returns. This article contains general information only and does not consider individual objectives, taxation position or financial needs. Nor does this constitute a recommendation of the suitability of any investment strategy for a particular investor. It is not an offer to buy or sell or a solicitation of an offer to buy or sell any security or instrument or to participate in any trading strategy to any person in any jurisdiction in which such an offer or solicitation is not authorised or to any person to whom it would be unlawful to market such an offer or solicitation.
When you access a shared link of third-party websites, you are leaving our website and assume total responsibility and risk for your use of the third-party websites. We make no representation as to the completeness or accuracy of information provided at these websites nor do we endorse the content and information contained on those sites.